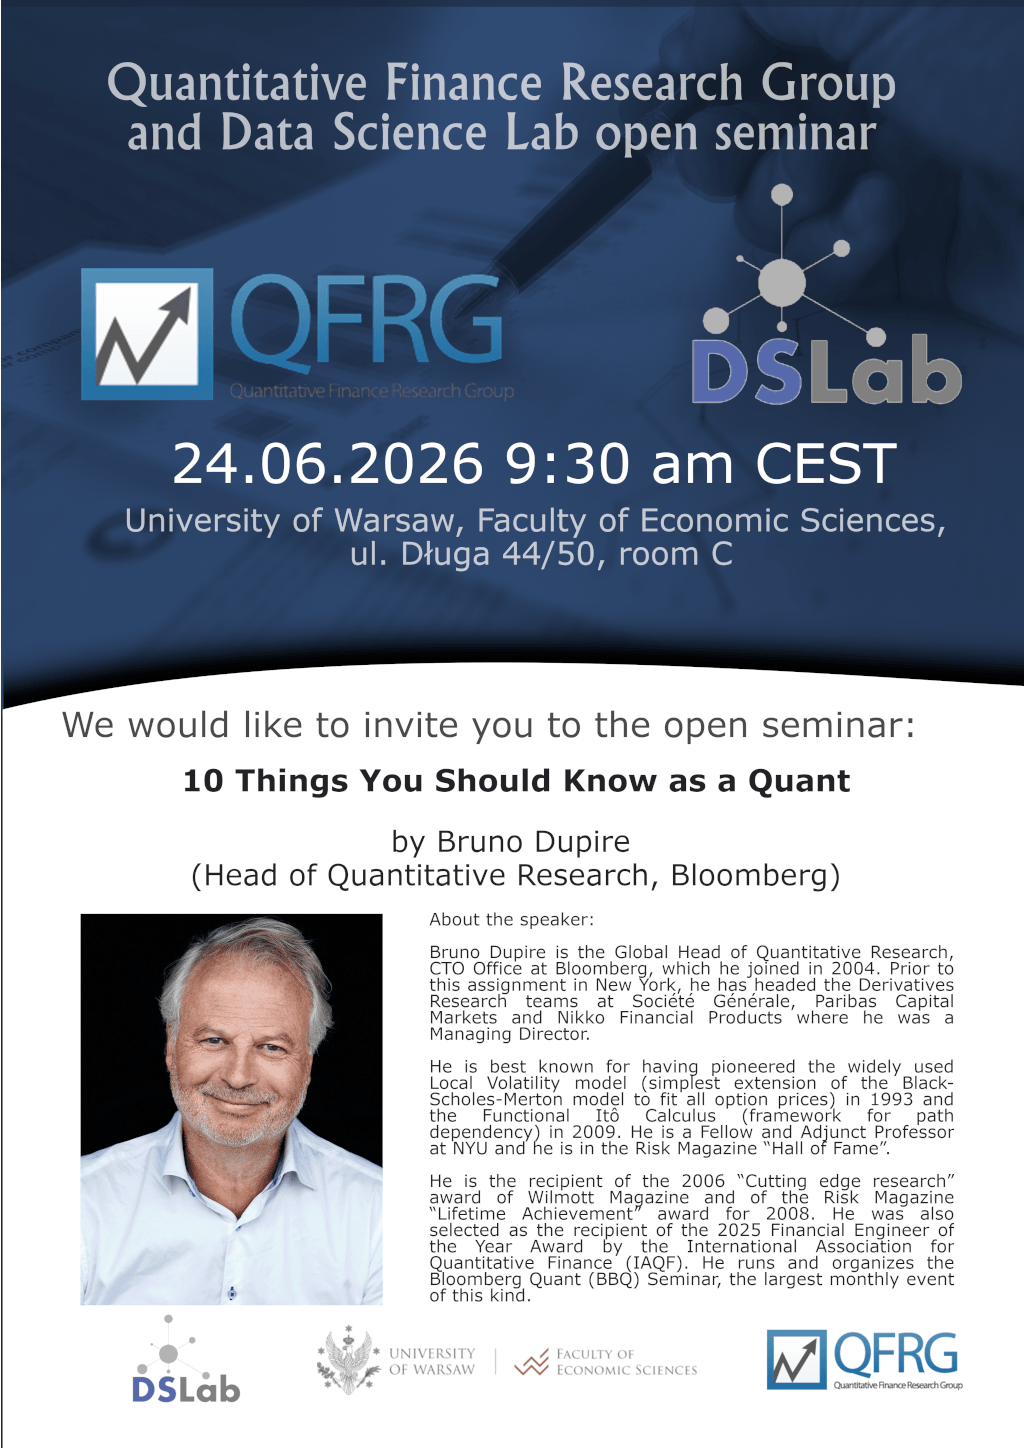

10 Things You Should Know as a Quant
About the speaker
Bruno Dupire is the Global Head of Quantitative Research, CTO Office at Bloomberg, which he joined in 2004. Prior to this assignment in New York, he has headed the Derivatives Research teams at Société Générale, Paribas Capital Markets and Nikko Financial Products where he was a Managing Director. He is best known for having pioneered the widely used Local Volatility model (simplest extension of the BlackScholes-Merton model to fit all option prices) in 1993 and the Functional Itô Calculus (framework for path dependency) in 2009. He is a Fellow and Adjunct Professor at NYU and he is in the Risk Magazine “Hall of Fame”. He is the recipient of the 2006 “Cutting edge research” award of Wilmott Magazine and of the Risk Magazine “Lifetime Achievement” award for 2008. He was also selected as the recipient of the 2025 Financial Engineer of the Year Award by the International Association for Quantitative Finance (IAQF). He runs and organizes the Bloomberg Quant (BBQ) Seminar, the largest monthly event of this kind.