
Eurex Conference 2012
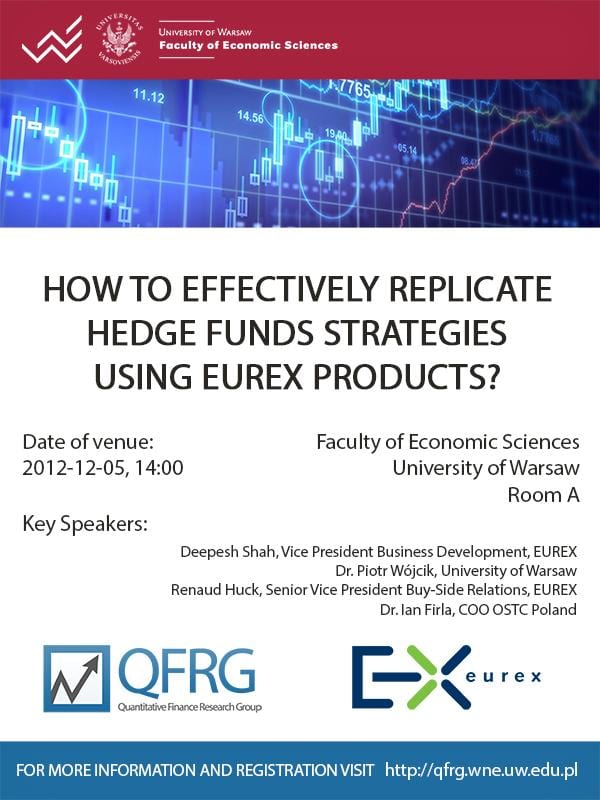
The Quantitative Finance Research Group and Eurex Exchange invite everyone interested to attend the conference:
HOW TO EFFECTIVELY REPLICATE
HEDGE FUNDS STRATEGIES
USING EUREX PRODUCTS?
2012-12-05, 14:00
[University of Warsaw
Faculty of Economic Sciences
Room A](contact-us)
Programme of the conference:
| 14.00-14.10 | Reception desk | |
| 14.10-14.20 | QFRG | opening remarks(slides) |
| 14.20-14.50 | Deepesh Shah, VP Business Development | EUREX: EUREX/Deutsche Börse activities focused on cooperation of business and science |
| 14.50-15.20 | QFRG Group #1, University of Warsaw | Replicating Hedge Fund Strategies using Eurex products |
| 15.20-15.50 | Dr. Piotr Wójcik, University of Warsaw | High-Frequency Data Modelling with R language |
| 15.50-16.05 | Coffee break | |
| 16.05-16.35 | Renaud Huck, SVP Buy-Side Relations, EUREX | The changing nature and landscape of the European hedge fund industry |
| 16.35-17.05 | QFRG Group #2, University of Warsaw | Replicating long/short hedge fund strategies using time-varying linear regression models |
| 17.05-17.20 | Coffee break | |
| 17.20-17.50 | Dr. Ian Firla, OSTC Poland | Potential careers in global trading for quantitative specialists. Application of quantitative methods in in real-world trading scenarios |
| 17.50-18.20 | Dr. Piotr Arendarski, University of Warsaw | Forecasting of time-series using methodology based on ARIMA models and genetic programming |
| 18.20-18.30 | Final remarks and Conference closing |
Last updated: 13 October 2022